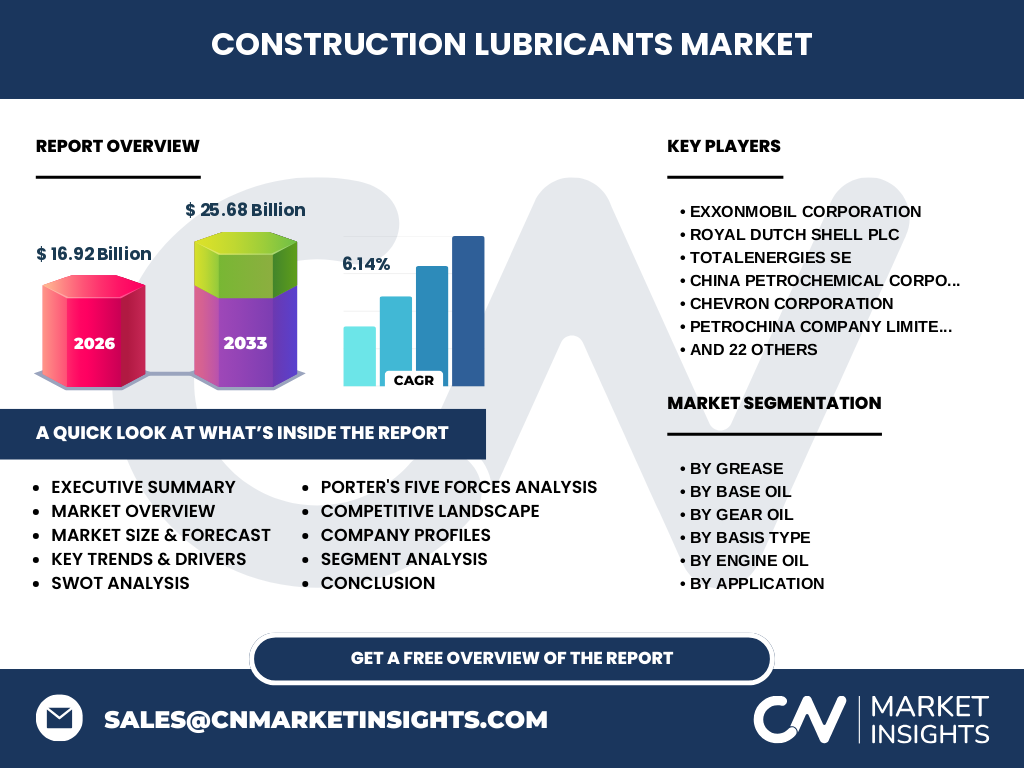
Market overview of the Construction Lubricants Market
Our analysis indicates that the Construction Lubricants Market is valued at 16.92 Billion in 2026. This sector encompasses specialized fluids, greases, and oils engineered to reduce friction, dissipate heat, and prevent wear in heavy-duty machinery operating across demanding civil infrastructure and building sites globally.
Key market drivers, restraints, challenges, and opportunities
Rapid urbanization and massive infrastructure investments act as primary catalysts, while stringent environmental regulations regarding base oil toxicity pose significant restraints. Industry participants like ExxonMobil Corporation and Royal Dutch Shell plc navigate logistical hurdles by developing eco-friendly formulations to capture high-growth opportunities.
Emerging trends and growth patterns in the Construction Lubricants Market
The shift toward biodegradable hydraulic fluids and synthetic base oils represents a major industry trend. Contractors increasingly demand high-performance lubricants that extend equipment maintenance intervals, directly lowering total operating costs for heavy construction vehicles and earthmoving fleets.
COVID-19 impact analysis and recovery trajectory
Supply chain disruptions and localized lockdowns temporarily contracted heavy machinery utilization. However, government stimulus packages targeting infrastructure revitalization accelerated the recovery trajectory, allowing industry leaders like Chevron Corporation and TotalEnergies SE to rebound rapidly through diversified supply networks.
Competitive landscape and strategic market concentration
The industry features moderate concentration, dominated by multinational giants such as China Petrochemical Corporation (Sinopec), BP p.l. c., and PetroChina Company Limited. These key players leverage advanced R&D and global distribution networks to maintain market dominance against regional lubricant blenders.
Executive summary of the Construction Lubricants Market
Driven by robust infrastructure investments, the Construction Lubricants Market is projected to expand significantly. Our research highlights synthetic oil adoption and specialized grease formulations as critical vectors for margin expansion among major manufacturers like FUCHS Petrolub SE and Valvoline Inc.
Market forecast from 2027 to 2033
Based on our econometric modeling, the Construction Lubricants Market is forecast to reach 25.68 Billion by 2033. This expansion represents a steady compound annual growth rate (CAGR) of 6.14%, fueled by continuous civil engineering projects worldwide.
Segmentation analysis across product and application categories
Our analysis segments the market by grease (Lithium-Based, Calcium-Based, Complex), base oil (Synthetic, Mineral), gear oil, basis type (Hydraulic Fluid, Engine Oil, Gear Oil, ATF, Grease, Compressor Oil), engine oil types, application (Earthmoving, Material Handling, Heavy Vehicles), compressor oil, hydraulic fluids, and ATF variants.
Regional market analysis and geographic performance
Geographic performance varies significantly, with Asia-Pacific leading consumption due to aggressive urbanization in emerging economies. North America and Europe follow closely, driven by stringent machinery efficiency standards and high adoption rates of advanced synthetic gear and engine oils.
In-depth regional review of key growth zones
Rapid infrastructure development across developing Asian markets creates sustained demand for affordable mineral-based formulations. Conversely, mature European and North American territories enforce strict environmental mandates, accelerating the regional transition toward biodegradable hydraulic fluids and premium synthetic lubricants.
Company profiles and strategic market positioning
Leading entities like PJSC LUKOIL, Idemitsu Kosan Co. Ltd., and Indian Oil Corporation Limited strategically position themselves by tailoring product lines to local climatic extremes. Specialty manufacturers like Klüber Lubrication and Schaeffer Manufacturing Co. focus on high-performance synthetic niche applications.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to the commoditized nature of crude base oils, whereas buyer power is high among large equipment fleet operators. Threat of substitutes is mitigated by strict original equipment manufacturer (OEM) performance certifications required for heavy machinery.
SWOT analysis of the Construction Lubricants Market
Strengths lie in robust chemical formulations ensuring high load-bearing capacity. Weaknesses include raw material price volatility. Opportunities abound in bio-based lubricants, while threats stem from regulatory compliance costs and potential global macroeconomic slowdowns affecting construction starts.
Value chain analysis from raw materials to end-users
The value chain originates with upstream crude oil refiners and chemical additive manufacturers. Midstream blending and packaging operations managed by firms like Phillips 66 Company and Morris Lubricants feed downstream distribution channels serving end-user construction fleets.
Investment insights and strategic recommendations
Investors should target companies investing heavily in biodegradable fluid technologies and synthetic base oil production facilities. Strategic partnerships with major construction equipment OEMs offer sustainable competitive advantages in a tightening regulatory environment.
Conclusion and key takeaways for stakeholders
The Construction Lubricants Market offers compelling growth prospects, supported by a projected valuation of 25.68 Billion by 2033. Success relies on aligning product portfolios with sustainability mandates and high-performance synthetic requirements.
Research methodology for baseline estimates
Our findings are triangulated by combining exhaustive trade registry data, primary stakeholder interviews with industry executives, and secondary macroeconomic indicators from global energy and manufacturing databases to ensure robust market sizing.
Scope of the report and coverage parameters
This report covers global consumption, production, and pricing dynamics across specified grease, base oil, gear oil, hydraulic fluid, and engine oil segments from 2026 through 2033, excluding minor unregulated regional lubricant blending operations.
Recent developments in corporate strategy and product launches
Recent developments feature major sustainability initiatives, such as TotalEnergies SE and Eni S. p. A. launching carbon-neutral lubricant lines. Additionally, strategic mergers among additive suppliers like The Lubrizol Corporation aim to enhance high-pressure anti-wear capabilities for modern heavy equipment.